Human-probability test defeats political donation deductions where banking records mask accommodation-entry fund layering rather than genuine contribu...
Electronic evidence and search statements in tax assessments require authenticity review and corroboration, while procedural manuals lack statutory fo...
Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
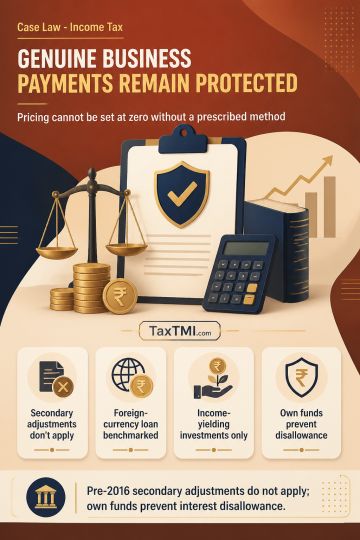
Commercially genuine exclusivity payments, transition-fee reimbursements and upfront discounts made to associated enterprises cannot be disregarded merely because their commercial structure is unusual or their expediency is questioned. Arm's length pricing cannot be fixed at nil without applying a prescribed transfer-pricing method; where the underlying primary adjustment fails, consequential notional interest also fails. Secondary-adjustment provisions do not apply to primary adjustments preceding 1 April 2016. Interest on a foreign-currency associated-enterprise loan is benchmarked at LIBOR plus 80 basis points. For exempt-income disallowance, only income-yielding investments are relevant and sufficient own interest-free funds preclude interest disallowance. Export turnover, TDS credit and education-cess claims were addressed through specified computation, verification and retrospective-amendment principles.
Commercially genuine exclusivity payments, transition-fee reimbursements and upfront discounts made to associated enterprises cannot be disregarded merely because their commercial structure is unusual or their expediency is questioned. Arm's length pricing cannot be fixed at nil without applying a prescribed transfer-pricing method; where the underlying primary adjustment fails, consequential notional interest also fails. Secondary-adjustment provisions do not apply to primary adjustments preceding 1 April 2016. Interest on a foreign-currency associated-enterprise loan is benchmarked at LIBOR plus 80 basis points. For exempt-income disallowance, only income-yielding investments are relevant and sufficient own interest-free funds preclude interest disallowance. Export turnover, TDS credit and education-cess claims were addressed through specified computation, verification and retrospective-amendment principles.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920