Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
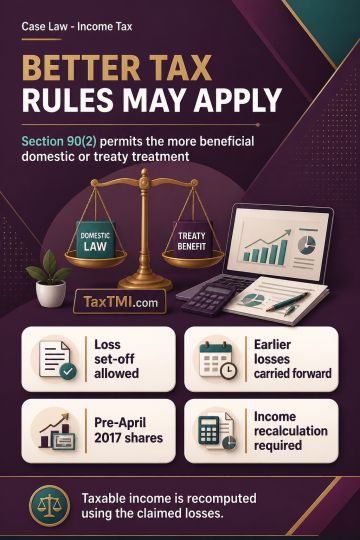
Section 90(2) permits a taxpayer to elect the more beneficial treatment available under domestic tax law or the India-Mauritius DTAA; treaty treatment cannot be imposed where the domestic-law position is more favourable. This principle supports setting off current and brought-forward long-term capital losses on shares acquired before 1 April 2017 against taxable capital gains from shares acquired thereafter. The claimed losses are to be considered in recomputing taxable income where the taxpayer validly exercises the beneficial statutory option.
Section 90(2) permits a taxpayer to elect the more beneficial treatment available under domestic tax law or the India-Mauritius DTAA; treaty treatment cannot be imposed where the domestic-law position is more favourable. This principle supports setting off current and brought-forward long-term capital losses on shares acquired before 1 April 2017 against taxable capital gains from shares acquired thereafter. The claimed losses are to be considered in recomputing taxable income where the taxpayer validly exercises the beneficial statutory option.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI