Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
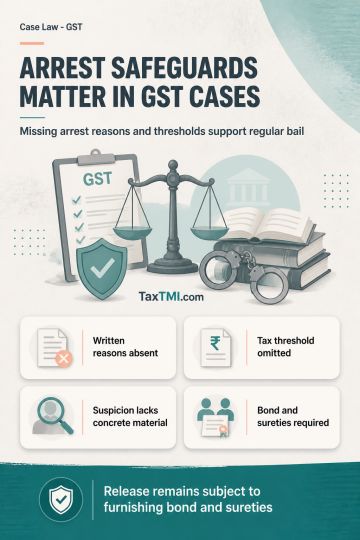
Sections 69 and 132 of the CGST Act are addressed in relation to regular bail for allegations of fraudulent invoices, wrongful input tax credit, falsified records and shell entities. Arrest requires recorded reasons to believe tax evasion or the specified conditions under section 132. The absence of those reasons in the arrest authorisation and memo, together with omission of the applicable tax-evasion threshold relevant to conviction, is treated as indicating suspicion rather than concrete material. These deficiencies support release on regular bail, subject to furnishing a bond and sureties.
Sections 69 and 132 of the CGST Act are addressed in relation to regular bail for allegations of fraudulent invoices, wrongful input tax credit, falsified records and shell entities. Arrest requires recorded reasons to believe tax evasion or the specified conditions under section 132. The absence of those reasons in the arrest authorisation and memo, together with omission of the applicable tax-evasion threshold relevant to conviction, is treated as indicating suspicion rather than concrete material. These deficiencies support release on regular bail, subject to furnishing a bond and sureties.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918