Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
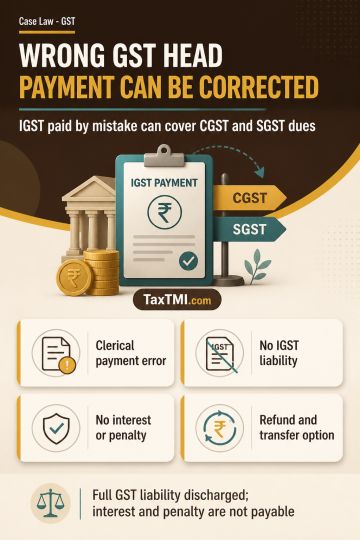
Inadvertent payment of GST under the IGST head, where CGST and SGST were actually payable and no IGST liability existed, is treated as a clerical error rather than a payment made under a misconception that the supply was inter-State. Section 77(2) therefore does not apply. Where the full GST liability has effectively been discharged, interest and penalty are not payable. The amount remitted as IGST may be appropriated against the CGST and SGST liability; where procedurally required, refund and transfer of the amount may be sought.
Inadvertent payment of GST under the IGST head, where CGST and SGST were actually payable and no IGST liability existed, is treated as a clerical error rather than a payment made under a misconception that the supply was inter-State. Section 77(2) therefore does not apply. Where the full GST liability has effectively been discharged, interest and penalty are not payable. The amount remitted as IGST may be appropriated against the CGST and SGST liability; where procedurally required, refund and transfer of the amount may be sought.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI