Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Page of 4920
Press 'Enter' after typing page number.
1941 to 1960 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
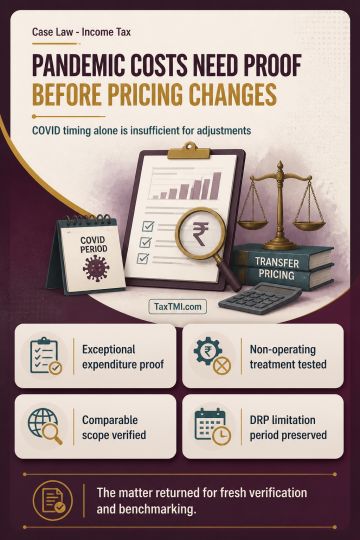
COVID-19 adjustments in transfer-pricing benchmarking require proof of exceptional pandemic expenditure, its non-operating character, and a materially different impact on comparables; pandemic timing alone is insufficient. TNMM also requires consistent treatment of operating and non-operating items for the tested party and comparables, including foreign-exchange effects from revenue transactions and depreciation on business assets. Internal CUP for software support services requires transaction-level comparability of contractual scope, functions, assets, risks, personnel, volume, duration and market conditions, with reliable adjustments for material differences. Transfer-pricing adjustments were remanded for fresh verification and benchmarking. A final assessment following timely draft assessment and DRP directions remains within the separate DRP-related limitation period.
COVID-19 adjustments in transfer-pricing benchmarking require proof of exceptional pandemic expenditure, its non-operating character, and a materially different impact on comparables; pandemic timing alone is insufficient. TNMM also requires consistent treatment of operating and non-operating items for the tested party and comparables, including foreign-exchange effects from revenue transactions and depreciation on business assets. Internal CUP for software support services requires transaction-level comparability of contractual scope, functions, assets, risks, personnel, volume, duration and market conditions, with reliable adjustments for material differences. Transfer-pricing adjustments were remanded for fresh verification and benchmarking. A final assessment following timely draft assessment and DRP directions remains within the separate DRP-related limitation period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920