Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
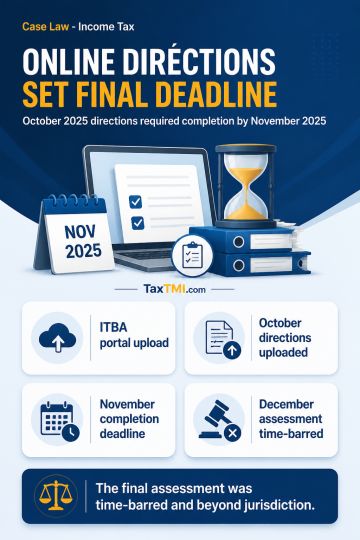
Electronic uploading of Dispute Resolution Panel directions on the ITBA portal constitutes valid and sufficient service for calculating the deadline for a final assessment under section 144C(13). Where directions were uploaded in October 2025, the final assessment had to be completed by the end of November 2025. Completion in December 2025 exceeded the prescribed limitation period, rendering the final assessment beyond jurisdiction and time-barred. Other grounds challenging the assessment remain open because limitation disposed of the matter.
Electronic uploading of Dispute Resolution Panel directions on the ITBA portal constitutes valid and sufficient service for calculating the deadline for a final assessment under section 144C(13). Where directions were uploaded in October 2025, the final assessment had to be completed by the end of November 2025. Completion in December 2025 exceeded the prescribed limitation period, rendering the final assessment beyond jurisdiction and time-barred. Other grounds challenging the assessment remain open because limitation disposed of the matter.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918