Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
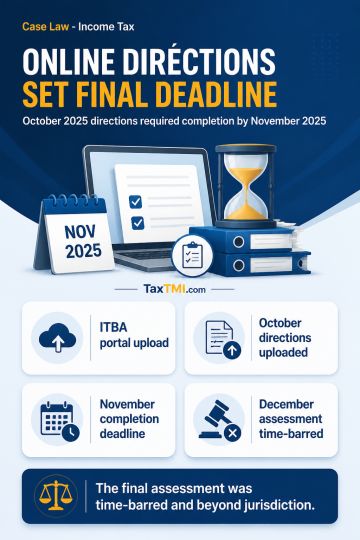
Electronic uploading of Dispute Resolution Panel directions on the ITBA portal constitutes valid and sufficient service for calculating the deadline for a final assessment under section 144C(13). Where directions were uploaded in October 2025, the final assessment had to be completed by the end of November 2025. Completion in December 2025 exceeded the prescribed limitation period, rendering the final assessment beyond jurisdiction and time-barred. Other grounds challenging the assessment remain open because limitation disposed of the matter.
Electronic uploading of Dispute Resolution Panel directions on the ITBA portal constitutes valid and sufficient service for calculating the deadline for a final assessment under section 144C(13). Where directions were uploaded in October 2025, the final assessment had to be completed by the end of November 2025. Completion in December 2025 exceeded the prescribed limitation period, rendering the final assessment beyond jurisdiction and time-barred. Other grounds challenging the assessment remain open because limitation disposed of the matter.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI