Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
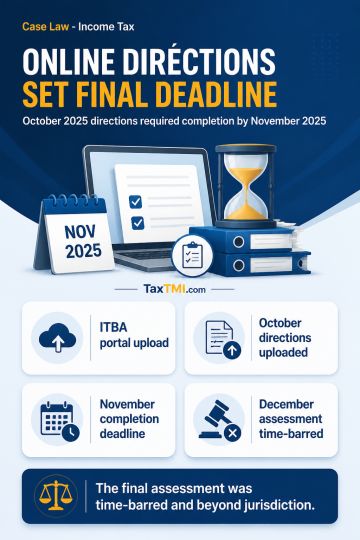
Electronic uploading of Dispute Resolution Panel directions on the ITBA portal constitutes valid and sufficient service for calculating the deadline for a final assessment under section 144C(13). Where directions were uploaded in October 2025, the final assessment had to be completed by the end of November 2025. Completion in December 2025 exceeded the prescribed limitation period, rendering the final assessment beyond jurisdiction and time-barred. Other grounds challenging the assessment remain open because limitation disposed of the matter.
Electronic uploading of Dispute Resolution Panel directions on the ITBA portal constitutes valid and sufficient service for calculating the deadline for a final assessment under section 144C(13). Where directions were uploaded in October 2025, the final assessment had to be completed by the end of November 2025. Completion in December 2025 exceeded the prescribed limitation period, rendering the final assessment beyond jurisdiction and time-barred. Other grounds challenging the assessment remain open because limitation disposed of the matter.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921