Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Double taxation of turnover requires holistic verification across separately registered units and permits limited rectification of overlapping assessm...
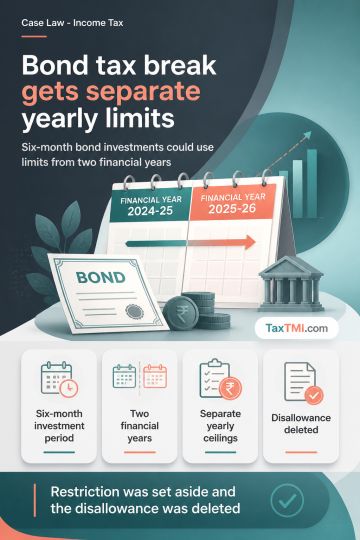
Section 54EC exemption for long-term capital gains may apply where specified bonds are purchased within six months of transfer across two financial years. For Assessment Year 2013-14, the investment ceiling operated independently for each financial year when the six-month period overlapped them, rather than as a single transaction-wide cap. The later amendment imposing an aggregate cap for the year of transfer and the succeeding financial year did not apply. Accordingly, restricting the exemption to one financial year's ceiling was set aside and the disallowance was deleted.
Section 54EC exemption for long-term capital gains may apply where specified bonds are purchased within six months of transfer across two financial years. For Assessment Year 2013-14, the investment ceiling operated independently for each financial year when the six-month period overlapped them, rather than as a single transaction-wide cap. The later amendment imposing an aggregate cap for the year of transfer and the succeeding financial year did not apply. Accordingly, restricting the exemption to one financial year's ceiling was set aside and the disallowance was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI