Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
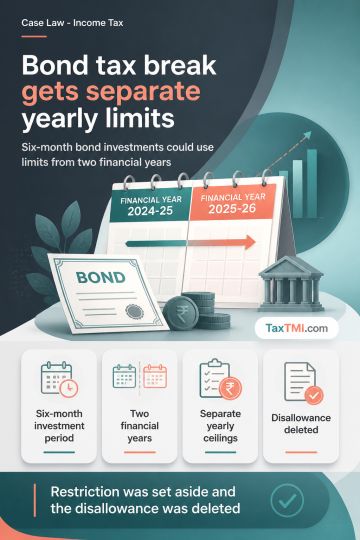
Section 54EC exemption for long-term capital gains may apply where specified bonds are purchased within six months of transfer across two financial years. For Assessment Year 2013-14, the investment ceiling operated independently for each financial year when the six-month period overlapped them, rather than as a single transaction-wide cap. The later amendment imposing an aggregate cap for the year of transfer and the succeeding financial year did not apply. Accordingly, restricting the exemption to one financial year's ceiling was set aside and the disallowance was deleted.
Section 54EC exemption for long-term capital gains may apply where specified bonds are purchased within six months of transfer across two financial years. For Assessment Year 2013-14, the investment ceiling operated independently for each financial year when the six-month period overlapped them, rather than as a single transaction-wide cap. The later amendment imposing an aggregate cap for the year of transfer and the succeeding financial year did not apply. Accordingly, restricting the exemption to one financial year's ceiling was set aside and the disallowance was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI