Customs procedure uniformity requires adoption of model clearance practices, subject to specific local requirements and infrastructure or geographical...
Territorial jurisdiction in income-tax appeals follows the assessing officer's location, not the Tribunal's seat or a subsequent acquirer's registered...
Transfer pricing comparables must reflect functional similarity, with diverse activities and asset profiles supporting exclusion from contract service...
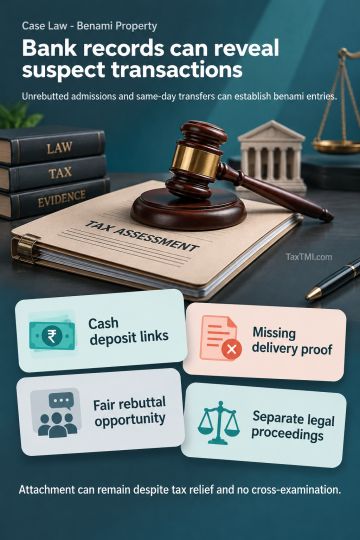
Unrebutted admissions and bank records linking cash deposits in intermediary companies to same-day transfers can establish benami accommodation entries. Banking-channel receipts and commercial records do not establish genuine sales where material invoice particulars and independent proof of delivery are absent. Natural justice requires a fair opportunity to know, answer and rebut adverse material, but does not confer an automatic right to cross-examine every witness. Income-tax assessment and benami proceedings serve different purposes. The benami enactment overrides the Income-tax Act, and deletion of an income-tax addition does not negate the benami character of a receipt.
Unrebutted admissions and bank records linking cash deposits in intermediary companies to same-day transfers can establish benami accommodation entries. Banking-channel receipts and commercial records do not establish genuine sales where material invoice particulars and independent proof of delivery are absent. Natural justice requires a fair opportunity to know, answer and rebut adverse material, but does not confer an automatic right to cross-examine every witness. Income-tax assessment and benami proceedings serve different purposes. The benami enactment overrides the Income-tax Act, and deletion of an income-tax addition does not negate the benami character of a receipt.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI

 of 4949


 Get Daily Updates