Brand promotion expenditure requires an established associated-enterprise arrangement for transfer pricing, while management cross-charges must accoun...
Reassessment after the ordinary limitation period requires the escaped-income threshold and independent sanction, without expanding jurisdiction throu...
Transfer pricing comparability requires turnover and functional analysis, alongside rules on exempt-income disallowance and amalgamation goodwill depr...
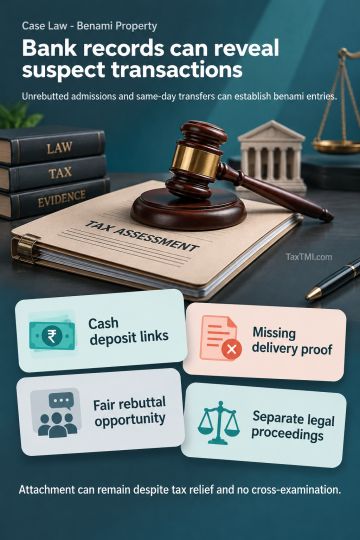
Unrebutted admissions and bank records linking cash deposits in intermediary companies to same-day transfers can establish benami accommodation entries. Banking-channel receipts and commercial records do not establish genuine sales where material invoice particulars and independent proof of delivery are absent. Natural justice requires a fair opportunity to know, answer and rebut adverse material, but does not confer an automatic right to cross-examine every witness. Income-tax assessment and benami proceedings serve different purposes. The benami enactment overrides the Income-tax Act, and deletion of an income-tax addition does not negate the benami character of a receipt.
Unrebutted admissions and bank records linking cash deposits in intermediary companies to same-day transfers can establish benami accommodation entries. Banking-channel receipts and commercial records do not establish genuine sales where material invoice particulars and independent proof of delivery are absent. Natural justice requires a fair opportunity to know, answer and rebut adverse material, but does not confer an automatic right to cross-examine every witness. Income-tax assessment and benami proceedings serve different purposes. The benami enactment overrides the Income-tax Act, and deletion of an income-tax addition does not negate the benami character of a receipt.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI





 Get Daily Updates