Brand promotion expenditure requires an established associated-enterprise arrangement for transfer pricing, while management cross-charges must accoun...
Reassessment after the ordinary limitation period requires the escaped-income threshold and independent sanction, without expanding jurisdiction throu...
Transfer pricing comparability requires turnover and functional analysis, alongside rules on exempt-income disallowance and amalgamation goodwill depr...
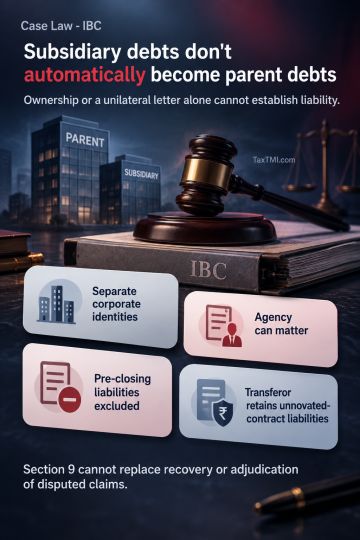
Separate corporate personality prevents a subsidiary's operational debt from being attributed to its holding company solely because of their relationship, unless the subsidiary acts as the parent's agent. Where business transfer terms exclude pre-closing liabilities and retain liabilities under unnovated contracts with the transferor, a unilateral letter referring to the transferor's outstanding dues cannot itself novate the agreement or establish the transferee's liability. Section 9 of the Insolvency and Bankruptcy Code cannot substitute for recovery or adjudication of a disputed commercial claim.
Separate corporate personality prevents a subsidiary's operational debt from being attributed to its holding company solely because of their relationship, unless the subsidiary acts as the parent's agent. Where business transfer terms exclude pre-closing liabilities and retain liabilities under unnovated contracts with the transferor, a unilateral letter referring to the transferor's outstanding dues cannot itself novate the agreement or establish the transferee's liability. Section 9 of the Insolvency and Bankruptcy Code cannot substitute for recovery or adjudication of a disputed commercial claim.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI





 Get Daily Updates