GST timing for Toll-Operate-Transfer concessions: concessionaires pay integrated tax when operation and maintenance expenses are charged to escrow acc...
Input tax credit conditions for concessional service rates permit limited same-line credits for hotels, catering, and electrically operated vehicle se...
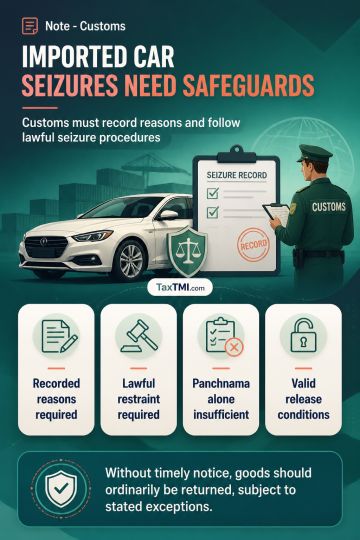
Customs seizure of an imported car requires recorded reasons to believe that the goods are liable to confiscation and compliance with prescribed forms of control. Where physical seizure is impracticable, custody may be retained under an undertaking after seizure, or a served non-dealing order may be used where seizure itself is impracticable. A panchnama alone does not satisfy those requirements. Seized goods must ordinarily be returned if confiscation notice is not issued within the statutory period, subject to a valid limited extension and the qualification for a valid provisional-release order. Provisional release applies only to goods lawfully seized and cannot regularise an unauthorised detention.
Customs seizure of an imported car requires recorded reasons to believe that the goods are liable to confiscation and compliance with prescribed forms of control. Where physical seizure is impracticable, custody may be retained under an undertaking after seizure, or a served non-dealing order may be used where seizure itself is impracticable. A panchnama alone does not satisfy those requirements. Seized goods must ordinarily be returned if confiscation notice is not issued within the statutory period, subject to a valid limited extension and the qualification for a valid provisional-release order. Provisional release applies only to goods lawfully seized and cannot regularise an unauthorised detention.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI