Approved gratuity fund provisions remain deductible despite general actual-payment requirements, preventing revision of the allowed gratuity deduction...
Verification of intangible software expenditure and duplicated disallowances requires record-based reassessment before depreciation and income computa...
Cash receipt aggregation requires a single transaction, event or occasion; separate partner capital contributions cannot attract cash-receipt penaltie...
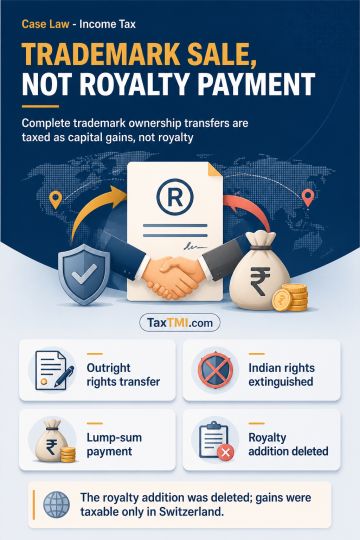
Under the India-Switzerland DTAA, consideration for an outright assignment of Indian trademark rights is distinguished from consideration for use or the right to use intellectual property. Transfer of all right, title, interest, goodwill, registration and enforcement rights, coupled with extinguishment of the transferor's Indian rights, characterises alienation of ownership; territorial, product and brand-protection covenants do not alone retain proprietorship. Lump-sum consideration not linked to future profits, productivity or use supports capital-gains treatment. Where the rights are not business property of an Indian permanent establishment, gains fall under Article 13(6) and are taxable only in Switzerland rather than as royalty under Article 12. The royalty addition was deleted.
Under the India-Switzerland DTAA, consideration for an outright assignment of Indian trademark rights is distinguished from consideration for use or the right to use intellectual property. Transfer of all right, title, interest, goodwill, registration and enforcement rights, coupled with extinguishment of the transferor's Indian rights, characterises alienation of ownership; territorial, product and brand-protection covenants do not alone retain proprietorship. Lump-sum consideration not linked to future profits, productivity or use supports capital-gains treatment. Where the rights are not business property of an Indian permanent establishment, gains fall under Article 13(6) and are taxable only in Switzerland rather than as royalty under Article 12. The royalty addition was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932