Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
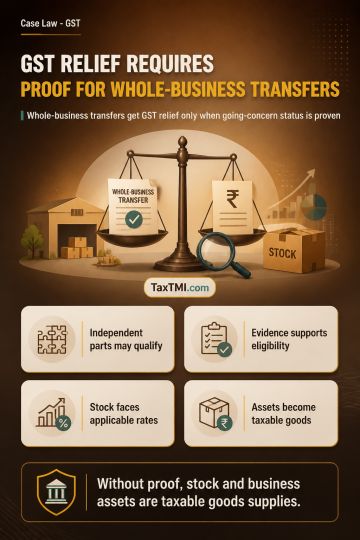
Transfer of an entire partnership business to a company without consideration may fall within GST supply, notwithstanding its occurrence outside the ordinary course of business. A transfer of a business undertaking as a going concern is classified as a supply of services rather than goods. The going-concern exemption applies only where the business, as a whole or independent part, satisfies that factual condition, requiring supporting evidence. If it does not qualify, the going-concern exception is unavailable and transferred stock and business assets are treated as taxable supplies of goods on cessation, at applicable rates.
Transfer of an entire partnership business to a company without consideration may fall within GST supply, notwithstanding its occurrence outside the ordinary course of business. A transfer of a business undertaking as a going concern is classified as a supply of services rather than goods. The going-concern exemption applies only where the business, as a whole or independent part, satisfies that factual condition, requiring supporting evidence. If it does not qualify, the going-concern exception is unavailable and transferred stock and business assets are treated as taxable supplies of goods on cessation, at applicable rates.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897