Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
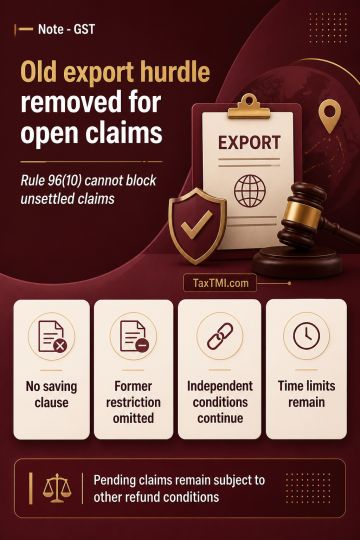
Omission of Rule 96(10) without a saving clause requires pending claims for refund of integrated tax paid on exports to be assessed without the former eligibility restriction. The Supreme Court treated the omission as applicable to proceedings pending on 08 October 2024, because no provision preserved the omitted sub-rule. Section 6 of the General Clauses Act does not save proceedings under an omitted rule, as it applies to repeal by a Central Act or Regulation rather than subordinate legislation. Independent refund conditions under the zero-rated supply, Section 54 and Rule 96 framework, including applicable procedures and limitation, continue to govern refund entitlement.
Omission of Rule 96(10) without a saving clause requires pending claims for refund of integrated tax paid on exports to be assessed without the former eligibility restriction. The Supreme Court treated the omission as applicable to proceedings pending on 08 October 2024, because no provision preserved the omitted sub-rule. Section 6 of the General Clauses Act does not save proceedings under an omitted rule, as it applies to repeal by a Central Act or Regulation rather than subordinate legislation. Independent refund conditions under the zero-rated supply, Section 54 and Rule 96 framework, including applicable procedures and limitation, continue to govern refund entitlement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886