Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Page of 4894
Press 'Enter' after typing page number.
241 to 260 of 97862 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
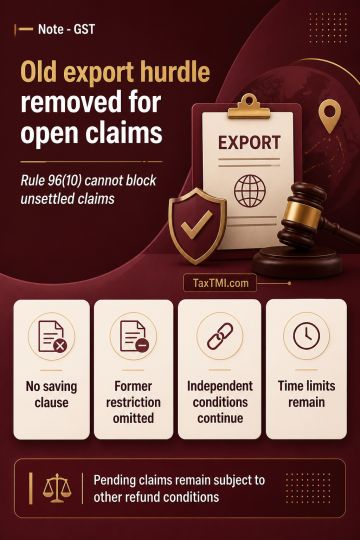
Omission of Rule 96(10) without a saving clause requires pending claims for refund of integrated tax paid on exports to be assessed without the former eligibility restriction. The Supreme Court treated the omission as applicable to proceedings pending on 08 October 2024, because no provision preserved the omitted sub-rule. Section 6 of the General Clauses Act does not save proceedings under an omitted rule, as it applies to repeal by a Central Act or Regulation rather than subordinate legislation. Independent refund conditions under the zero-rated supply, Section 54 and Rule 96 framework, including applicable procedures and limitation, continue to govern refund entitlement.
Omission of Rule 96(10) without a saving clause requires pending claims for refund of integrated tax paid on exports to be assessed without the former eligibility restriction. The Supreme Court treated the omission as applicable to proceedings pending on 08 October 2024, because no provision preserved the omitted sub-rule. Section 6 of the General Clauses Act does not save proceedings under an omitted rule, as it applies to repeal by a Central Act or Regulation rather than subordinate legislation. Independent refund conditions under the zero-rated supply, Section 54 and Rule 96 framework, including applicable procedures and limitation, continue to govern refund entitlement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894