Appellate jurisdiction over baggage imports is excluded, requiring confiscation challenges involving passenger-carried gold to proceed by statutory re...
Article 227 review permits intervention in arbitration only for manifest, patent inherent jurisdictional defects, not representational authority dispu...
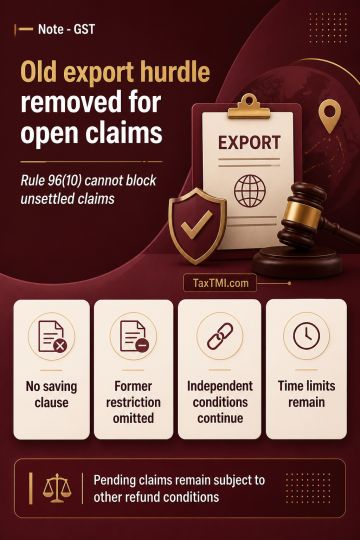
Omission of Rule 96(10) without a saving clause requires pending claims for refund of integrated tax paid on exports to be assessed without the former eligibility restriction. The Supreme Court treated the omission as applicable to proceedings pending on 08 October 2024, because no provision preserved the omitted sub-rule. Section 6 of the General Clauses Act does not save proceedings under an omitted rule, as it applies to repeal by a Central Act or Regulation rather than subordinate legislation. Independent refund conditions under the zero-rated supply, Section 54 and Rule 96 framework, including applicable procedures and limitation, continue to govern refund entitlement.
Omission of Rule 96(10) without a saving clause requires pending claims for refund of integrated tax paid on exports to be assessed without the former eligibility restriction. The Supreme Court treated the omission as applicable to proceedings pending on 08 October 2024, because no provision preserved the omitted sub-rule. Section 6 of the General Clauses Act does not save proceedings under an omitted rule, as it applies to repeal by a Central Act or Regulation rather than subordinate legislation. Independent refund conditions under the zero-rated supply, Section 54 and Rule 96 framework, including applicable procedures and limitation, continue to govern refund entitlement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI