Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
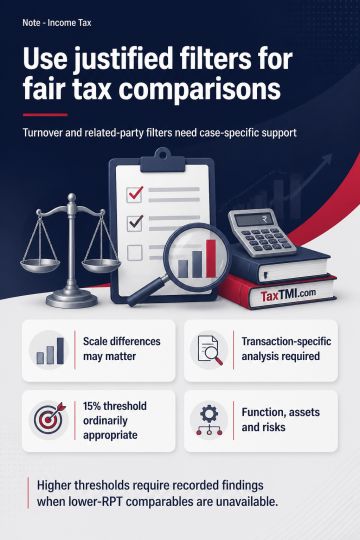
Transfer-pricing comparability under the transactional net margin method requires economically reliable uncontrolled benchmarks under Section 92C and Rule 10B. Turnover is not a standalone statutory bar, but material scale differences may justify excluding enterprises where brand value, intangibles, bargaining power, assets, risks or market conditions could affect margins. A turnover threshold must therefore be supported by transaction-specific comparability analysis rather than applied as a universal rule. Related-party transaction filters seek to reduce the influence of controlled dealings on comparable profitability. A 15% threshold is ordinarily appropriate where sufficient reliable comparables exist; a higher threshold requires a recorded finding that lower-RPT comparables are unavailable. Functional, asset and risk analysis remains essential, and appellate review may address disregard of statutory criteria or perverse findings.
Transfer-pricing comparability under the transactional net margin method requires economically reliable uncontrolled benchmarks under Section 92C and Rule 10B. Turnover is not a standalone statutory bar, but material scale differences may justify excluding enterprises where brand value, intangibles, bargaining power, assets, risks or market conditions could affect margins. A turnover threshold must therefore be supported by transaction-specific comparability analysis rather than applied as a universal rule. Related-party transaction filters seek to reduce the influence of controlled dealings on comparable profitability. A 15% threshold is ordinarily appropriate where sufficient reliable comparables exist; a higher threshold requires a recorded finding that lower-RPT comparables are unavailable. Functional, asset and risk analysis remains essential, and appellate review may address disregard of statutory criteria or perverse findings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888