Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
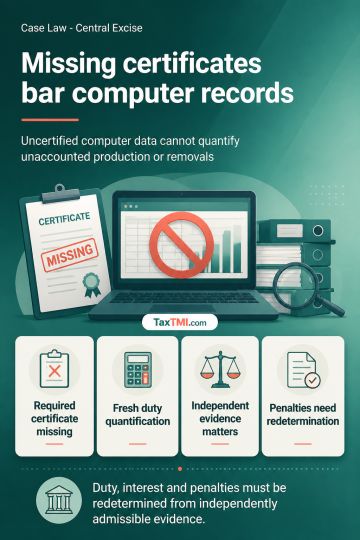
Electronic records used to establish clandestine manufacture and clearance require compliance with prescribed statutory conditions, including the requisite certificate; without it, CD data and computer printouts are inadmissible and cannot determine unaccounted production or removals. Duty demands founded on excluded electronic data require fresh quantification solely from independently admissible evidence. Cross-examination of investigation witnesses is not absolute: unretracted statements may be considered where no evidence of coercion or witness-specific prejudice from denial of cross-examination is shown. Such statements, together with invoices, transport, weighment and statutory records, may support independently established transactions, while interest and penalties must be redetermined with any duty liability ultimately found.
Electronic records used to establish clandestine manufacture and clearance require compliance with prescribed statutory conditions, including the requisite certificate; without it, CD data and computer printouts are inadmissible and cannot determine unaccounted production or removals. Duty demands founded on excluded electronic data require fresh quantification solely from independently admissible evidence. Cross-examination of investigation witnesses is not absolute: unretracted statements may be considered where no evidence of coercion or witness-specific prejudice from denial of cross-examination is shown. Such statements, together with invoices, transport, weighment and statutory records, may support independently established transactions, while interest and penalties must be redetermined with any duty liability ultimately found.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI