COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
Transfer-pricing comparability filters require fresh arm's-length analysis, while delayed receivables need separate reconsideration with working-capit...
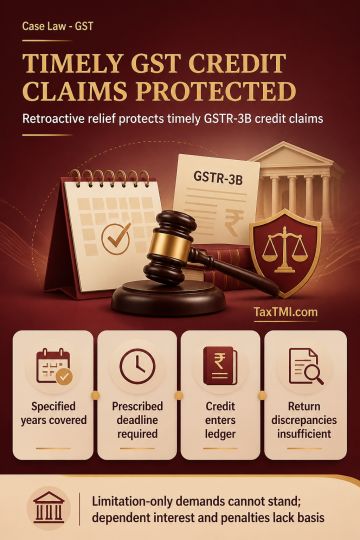
Retrospective section 16(5) permits input tax credit for specified financial years where claimed through GSTR-3B filed by the prescribed deadline, overriding the earlier limitation in section 16(4). GSTR-3B functions as the section 39 return for this purpose. Credit is availed when claimed and credited to the Electronic Credit Ledger; later utilisation does not constitute delayed availment. Discrepancies in GSTR-9 or GSTR-9C cannot by themselves extinguish credit already claimed through GSTR-3B. A demand founded solely on limitation cannot be sustained on new substantive grounds absent from the show-cause notice and original adjudication. Interest and penalty dependent exclusively on an invalid credit denial lack an independent basis.
Retrospective section 16(5) permits input tax credit for specified financial years where claimed through GSTR-3B filed by the prescribed deadline, overriding the earlier limitation in section 16(4). GSTR-3B functions as the section 39 return for this purpose. Credit is availed when claimed and credited to the Electronic Credit Ledger; later utilisation does not constitute delayed availment. Discrepancies in GSTR-9 or GSTR-9C cannot by themselves extinguish credit already claimed through GSTR-3B. A demand founded solely on limitation cannot be sustained on new substantive grounds absent from the show-cause notice and original adjudication. Interest and penalty dependent exclusively on an invalid credit denial lack an independent basis.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884