Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Commodity trading contracts are financial products when IFSC units trade deliverable goods, subject to specified commodity exclusions.
    Customs tariff values apply to edible oils, brass scrap, precious metals and areca nuts, with conditions for certain imports.
    Commodity trading as a financial service covers cross-border or foreign domestic shipments by IFSC units under applicable Indian laws.
    Anti-dumping duty exclusions for low ash metallurgical coke imports depend on compliance with specified customs procedures.
    Temporary imports under A.T.A. Carnets may receive extensions in the public interest, subject to carnet validity limits.
    Semiconductor manufacturing zone is designated with an Approval Committee and Inland Container Depot status for customs purposes.
    Preferential certificates of origin under the India-New Zealand trade agreement are available through designated agencies with specified scopes.
    Input tax credit for motor vehicle sales agents is addressed by an adapted GST clarification under state law.
    GST applicability to services follows central clarifications, with necessary adaptations for implementation under the state GST framework.
    Central excise and service tax appeals pending in Bengaluru are reassigned to designated officers for appellate decisions.
    Preferential certificates of origin for New Zealand exports are available electronically through authorised agencies on the Trade Connect platform.
    GST arrest protection under a binding instruction continues while the prohibition on further arrests remains in force.
    Pre-trial detention in GST input tax credit prosecutions is non-punitive and must be assessed against personal liberty.
    GST annual return late fees accrue daily and are capped by turnover, rather than automatically charged at the maximum.
    Electronic credit ledger blocking requires reasons to believe input tax credit was fraudulently claimed or is otherwise ineligible.
    Natural justice in GST interest recovery must guide consideration of an intimation following an appellate order's express reservation.
    E-invoice generation by suppliers: recipients face no transit penalty for supplier omissions when compliant documents accompany goods.
    Loose order slips do not justify GST on exempt supplies or repeat demands for recorded, tax-paid sales.
    Missing e-invoices and e-way bills can attract penalties, while penalty orders must set out the basis for decisions.
    Unaccounted stock confiscation can rest on signed physical inventory, while recurring legal issues bypass departmental appeal monetary limits.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Telegram Get Daily Updates

Unaccounted quarry sales establish suppressed business...

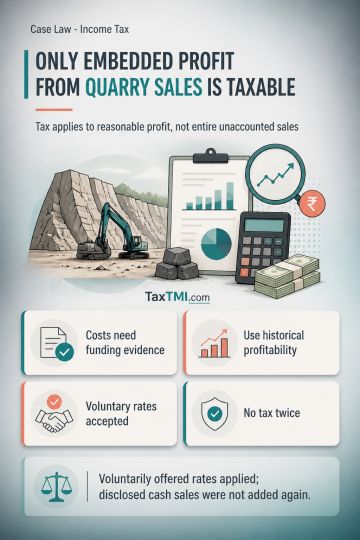
Unaccounted quarry sales: only reasonably estimated profit is taxable, while cash sales already disclosed cannot be taxed twice.

Contents
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Income Tax September 30, 2026 Case Laws AT
Unaccounted quarry sales establish suppressed business transactions, but only the profit reasonably embedded in those sales is taxable; extraction, production and operating costs cannot be treated as income absent evidence of unexplained funding. Profit estimation must have a rational link to the taxpayer's own historical results and accounted-business profitability; an unverified external gross-profit margin cannot be substituted for net profit. The voluntarily offered profit rates were accepted, displacing the higher rate. Cash sales captured in seized data cannot be added separately where aggregate records, annual accounts and GST disclosures show they were already included in disclosed turnover; a further profit addition would duplicate the same sales.

Topics

Acts Income Tax