Government water works contract GST concession applied before its withdrawal, while contractual tax reimbursement claims lay outside advance-ruling sc...
Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
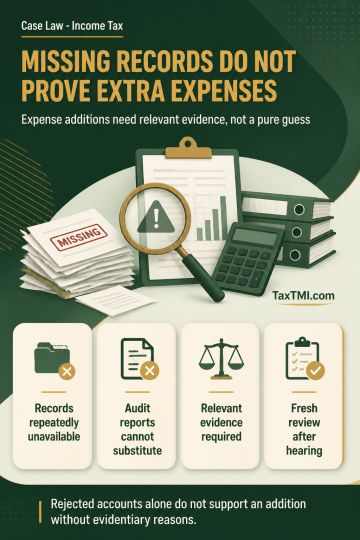
Rejection of books of account may be sustained where primary books, bills and vouchers are repeatedly not produced; an audit report does not replace records required for verification. Best-judgment disallowance of unverifiable expenditure must nevertheless rest on relevant material and bear a reasonable nexus to it, rather than amounting to a pure guess. Rejection of accounts alone does not justify an addition, and acceptance of recorded receipts or absence of objection to a proposed rate cannot supply evidentiary reasons. Adjacent-year audited financial statements, books and vouchers may be verified for fresh quantification after hearing.
Rejection of books of account may be sustained where primary books, bills and vouchers are repeatedly not produced; an audit report does not replace records required for verification. Best-judgment disallowance of unverifiable expenditure must nevertheless rest on relevant material and bear a reasonable nexus to it, rather than amounting to a pure guess. Rejection of accounts alone does not justify an addition, and acceptance of recorded receipts or absence of objection to a proposed rate cannot supply evidentiary reasons. Adjacent-year audited financial statements, books and vouchers may be verified for fresh quantification after hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI