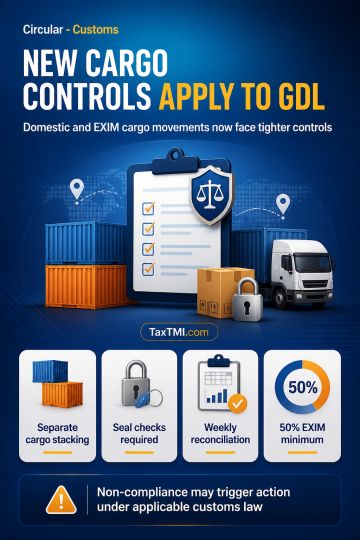
Customs-controlled cargo movement now includes GDL, subject to EXIM prioritisation, segregation, verification, reconciliation and enforcement safeguar...
GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
Page of 4927
Press 'Enter' after typing page number.
981 to 1000 of 98535 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Penalty for under-reported income is not automatically attracted merely because a first return is filed in response to a reassessment notice and accepted without variation. The statutory trigger must be read with the exclusion for a bona fide explanation and full disclosure of material facts. The use of "may" preserves discretion in imposing penalty. Relevant indicators of bona fides include audit-related delay, an undisposed request to file the return, prompt filing after notice, verified declared figures, and payment of tax and interest. Treating bona fides as irrelevant without reasoned consideration is inconsistent with this framework; on the stated facts, the penalty was deleted.
Penalty for under-reported income is not automatically attracted merely because a first return is filed in response to a reassessment notice and accepted without variation. The statutory trigger must be read with the exclusion for a bona fide explanation and full disclosure of material facts. The use of "may" preserves discretion in imposing penalty. Relevant indicators of bona fides include audit-related delay, an undisposed request to file the return, prompt filing after notice, verified declared figures, and payment of tax and interest. Treating bona fides as irrelevant without reasoned consideration is inconsistent with this framework; on the stated facts, the penalty was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927