Government water works contract GST concession applied before its withdrawal, while contractual tax reimbursement claims lay outside advance-ruling sc...
Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
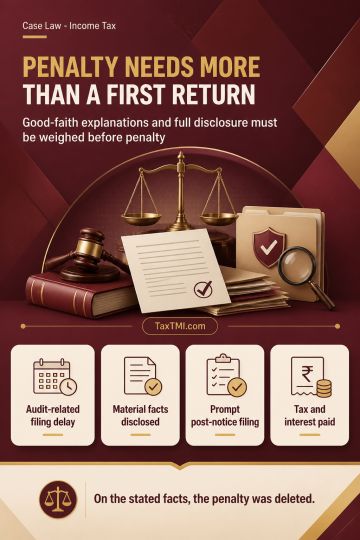
Penalty for under-reported income is not automatically attracted merely because a first return is filed in response to a reassessment notice and accepted without variation. The statutory trigger must be read with the exclusion for a bona fide explanation and full disclosure of material facts. The use of "may" preserves discretion in imposing penalty. Relevant indicators of bona fides include audit-related delay, an undisposed request to file the return, prompt filing after notice, verified declared figures, and payment of tax and interest. Treating bona fides as irrelevant without reasoned consideration is inconsistent with this framework; on the stated facts, the penalty was deleted.
Penalty for under-reported income is not automatically attracted merely because a first return is filed in response to a reassessment notice and accepted without variation. The statutory trigger must be read with the exclusion for a bona fide explanation and full disclosure of material facts. The use of "may" preserves discretion in imposing penalty. Relevant indicators of bona fides include audit-related delay, an undisposed request to file the return, prompt filing after notice, verified declared figures, and payment of tax and interest. Treating bona fides as irrelevant without reasoned consideration is inconsistent with this framework; on the stated facts, the penalty was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI