Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
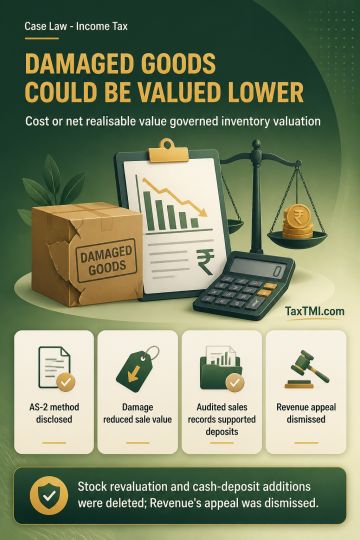
Damaged guar gum inventory valued under Accounting Standard-2 at cost or net realisable value, whichever is lower, may be written down where damage prevents recovery at normal sale value; revaluation cannot displace that disclosed method. Non-moving or deteriorated inventory may similarly be written off when corrosion or wear and tear reduces its value. Cash deposits during demonetisation, already recorded as sales in audited books and supported by sale bills, delivery challans, and sales and stock registers, are not unexplained money without contrary material. The additions for stock revaluation and cash deposits were deleted, and the Revenue's appeal was dismissed.
Damaged guar gum inventory valued under Accounting Standard-2 at cost or net realisable value, whichever is lower, may be written down where damage prevents recovery at normal sale value; revaluation cannot displace that disclosed method. Non-moving or deteriorated inventory may similarly be written off when corrosion or wear and tear reduces its value. Cash deposits during demonetisation, already recorded as sales in audited books and supported by sale bills, delivery challans, and sales and stock registers, are not unexplained money without contrary material. The additions for stock revaluation and cash deposits were deleted, and the Revenue's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI