Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
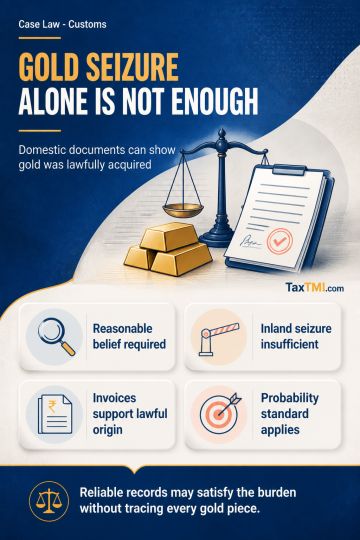
Reverse burden for notified gold under section 123 arises only where tangible material supports a reasonable belief of smuggling; inland seizure or absence of foreign markings alone is insufficient. Assessment requires cumulative consideration of carriage, the article's nature, statements, documentary provenance and accounting trail. Registered suppliers and tax invoices supporting domestically acquired gold may establish lawful provenance unless shown to be false or unconnected with business stock. The claimant may discharge the burden on a preponderance of probability through reliable documents and circumstances, without proving uninterrupted physical identity of fungible gold unless circumstances warrant it.
Reverse burden for notified gold under section 123 arises only where tangible material supports a reasonable belief of smuggling; inland seizure or absence of foreign markings alone is insufficient. Assessment requires cumulative consideration of carriage, the article's nature, statements, documentary provenance and accounting trail. Registered suppliers and tax invoices supporting domestically acquired gold may establish lawful provenance unless shown to be false or unconnected with business stock. The claimant may discharge the burden on a preponderance of probability through reliable documents and circumstances, without proving uninterrupted physical identity of fungible gold unless circumstances warrant it.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI