Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
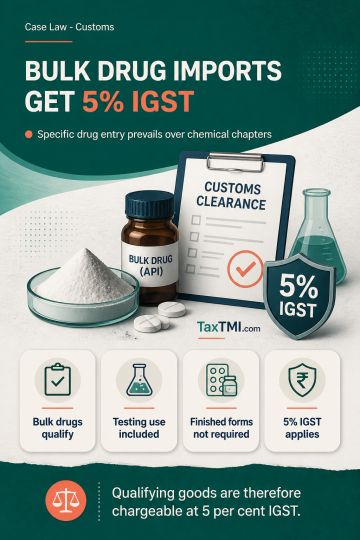
Bulk drugs and active pharmaceutical ingredients qualify as drugs and medicines where they meet the applicable pharmaceutical definitions, even when imported for examination, testing, clinical research, bioavailability or bioequivalence studies. The description-based IGST rate entry covering drugs and medicines under any chapter applies to qualifying APIs, provided they do not fall within the specified nil-rate exclusion. The entry is not restricted to finished formulations under Chapter 30. Where APIs are chemically classifiable under Chapters 28 or 29, the specific drug entry prevails over the general inorganic or organic chemical entries. Qualifying goods are therefore chargeable at 5 per cent IGST.
Bulk drugs and active pharmaceutical ingredients qualify as drugs and medicines where they meet the applicable pharmaceutical definitions, even when imported for examination, testing, clinical research, bioavailability or bioequivalence studies. The description-based IGST rate entry covering drugs and medicines under any chapter applies to qualifying APIs, provided they do not fall within the specified nil-rate exclusion. The entry is not restricted to finished formulations under Chapter 30. Where APIs are chemically classifiable under Chapters 28 or 29, the specific drug entry prevails over the general inorganic or organic chemical entries. Qualifying goods are therefore chargeable at 5 per cent IGST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI