Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
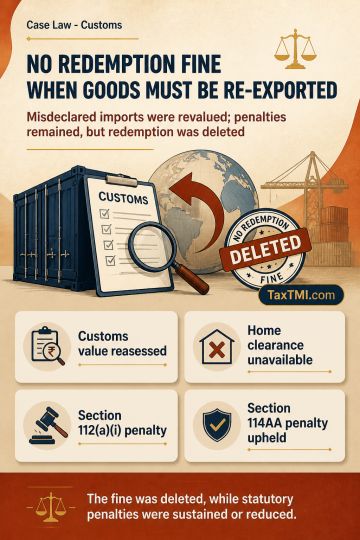
Admitted misdeclaration of imported used printers and accessories justified re-determination of customs value, which was sustained. Conditional redemption upon re-export is not permitted under the statutory scheme: where prohibited misdeclared goods cannot be cleared for home consumption and may only be re-exported, redemption fine is unjustified and was deleted. Misdeclaration of prohibited imported goods continues to attract penalty under Section 112(a)(i), although the penalty was reduced because redemption was unavailable. Section 114AA applies to business transactions involving false or incorrect information, rather than only fraudulent exports, and that penalty was sustained.
Admitted misdeclaration of imported used printers and accessories justified re-determination of customs value, which was sustained. Conditional redemption upon re-export is not permitted under the statutory scheme: where prohibited misdeclared goods cannot be cleared for home consumption and may only be re-exported, redemption fine is unjustified and was deleted. Misdeclaration of prohibited imported goods continues to attract penalty under Section 112(a)(i), although the penalty was reduced because redemption was unavailable. Section 114AA applies to business transactions involving false or incorrect information, rather than only fraudulent exports, and that penalty was sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI