Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
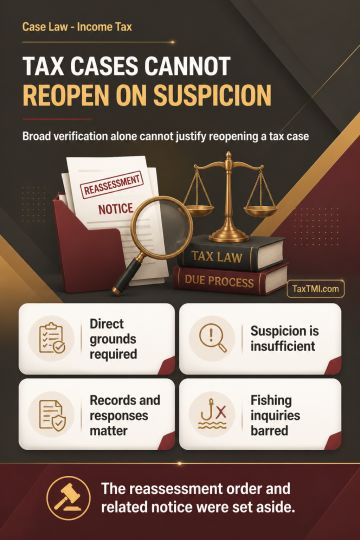
Reassessment under section 148A requires information that rationally and directly suggests income escapement; mere suspicion, a need for further scrutiny, or a verification objective is insufficient. The material and the taxpayer's response must be considered in a speaking order before a case is treated as fit for reassessment. Treating an entire trust's expenditure over several years as unexplained, despite accounts, bank records and vouchers, without identifying a false explanation or unaccounted amount, constitutes an impermissible roving or fishing inquiry. The reassessment order and consequential notice for the relevant assessment year were set aside.
Reassessment under section 148A requires information that rationally and directly suggests income escapement; mere suspicion, a need for further scrutiny, or a verification objective is insufficient. The material and the taxpayer's response must be considered in a speaking order before a case is treated as fit for reassessment. Treating an entire trust's expenditure over several years as unexplained, despite accounts, bank records and vouchers, without identifying a false explanation or unaccounted amount, constitutes an impermissible roving or fishing inquiry. The reassessment order and consequential notice for the relevant assessment year were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939