Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
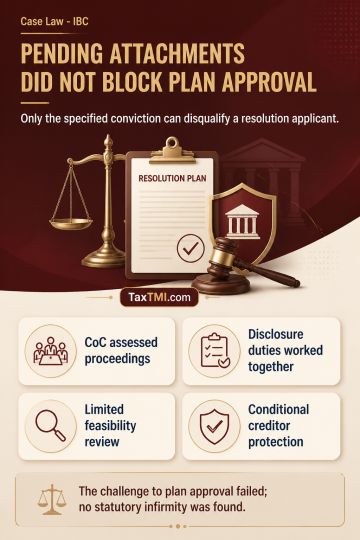
Pending PMLA attachment proceedings do not by themselves disqualify a prospective resolution applicant; disqualification requires the conviction specified under section 29A. Disclosure requirements under Regulation 39(1)(c) operate harmoniously with section 29A, particularly where the CoC knew of, assessed, and deliberated on the proceedings before plan approval. Review of the CoC's commercial assessment of plan feasibility, viability, and implementation remains confined to statutory approval and appeal grounds. A plan may conditionally protect a disputed creditor's position by automatically revising distribution if secured-financial-creditor status is later established. On these grounds, the challenge to plan approval failed, with no statutory infirmity found.
Pending PMLA attachment proceedings do not by themselves disqualify a prospective resolution applicant; disqualification requires the conviction specified under section 29A. Disclosure requirements under Regulation 39(1)(c) operate harmoniously with section 29A, particularly where the CoC knew of, assessed, and deliberated on the proceedings before plan approval. Review of the CoC's commercial assessment of plan feasibility, viability, and implementation remains confined to statutory approval and appeal grounds. A plan may conditionally protect a disputed creditor's position by automatically revising distribution if secured-financial-creditor status is later established. On these grounds, the challenge to plan approval failed, with no statutory infirmity found.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4879