Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Non-participating bidders cannot disturb concluded liquidation sales on speculative prejudice, while costs for such challenges must remain proportiona...
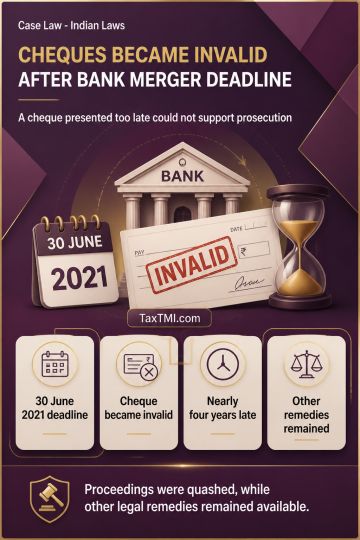
Post-merger validity of cheques is a mandatory precondition to prosecution for cheque dishonour under Section 138. Merger terms made cheques drawn on Syndicate Bank invalid after 30 June 2021. A cheque presented nearly four years after that deadline was therefore not a valid instrument, even if dishonoured. Because presentation within the instrument's validity period is essential to Section 138 liability, proceedings founded on the invalid cheque were quashed. The complainant retained liberty to pursue other remedies available in law.
Post-merger validity of cheques is a mandatory precondition to prosecution for cheque dishonour under Section 138. Merger terms made cheques drawn on Syndicate Bank invalid after 30 June 2021. A cheque presented nearly four years after that deadline was therefore not a valid instrument, even if dishonoured. Because presentation within the instrument's validity period is essential to Section 138 liability, proceedings founded on the invalid cheque were quashed. The complainant retained liberty to pursue other remedies available in law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881