Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
Way Leave Permissions cannot be retrospectively revived through insolvency plans, and affected infrastructure holders require safety review and hearin...
Inter-terminal container movement requires customs escort, permit reconciliation, and indemnity, while delayed DPD cargo may move to designated CFS ya...
Page of 4884
Press 'Enter' after typing page number.
701 to 720 of 97661 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
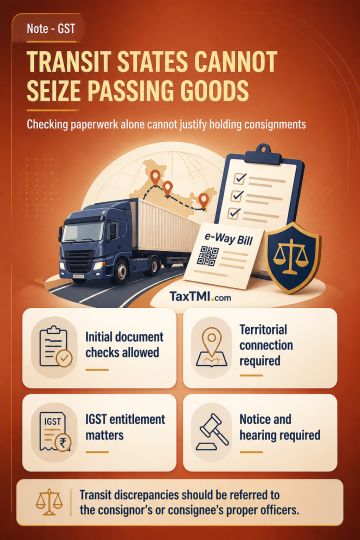
State GST officers may conduct initial document verification of inter-State consignments but cannot detain, seize or confiscate goods merely passing through their State. Cross-empowerment under CGST and IGST laws requires both administrative allocation of the taxpayer to the State and assignment of the relevant proper-officer function; it is not unrestricted authority. Coercive action under Sections 129 and 130 additionally requires territorial and fiscal nexus, including the State's entitlement to IGST apportionment under Section 17. For consignments originating and destined outside the intercepting State, discrepancies should be referred to the consignor's or consignee's proper officers. Confiscation requires statutory grounds, material supporting intent to evade tax where applicable, and notice and hearing; transit checks cannot become valuation assessments.
State GST officers may conduct initial document verification of inter-State consignments but cannot detain, seize or confiscate goods merely passing through their State. Cross-empowerment under CGST and IGST laws requires both administrative allocation of the taxpayer to the State and assignment of the relevant proper-officer function; it is not unrestricted authority. Coercive action under Sections 129 and 130 additionally requires territorial and fiscal nexus, including the State's entitlement to IGST apportionment under Section 17. For consignments originating and destined outside the intercepting State, discrepancies should be referred to the consignor's or consignee's proper officers. Confiscation requires statutory grounds, material supporting intent to evade tax where applicable, and notice and hearing; transit checks cannot become valuation assessments.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884