Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
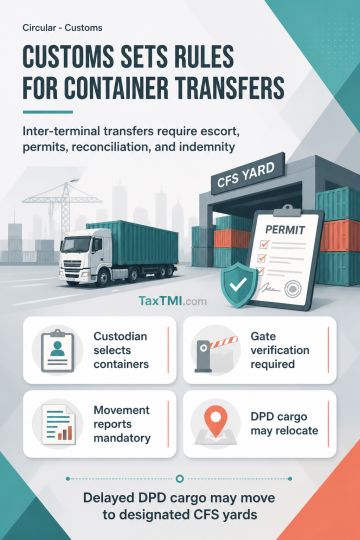
Inter-terminal container movement requires customs escort, permit reconciliation, and indemnity, while delayed DPD cargo may move to designated CFS ya...
Page of 593
Press 'Enter' after typing page number.
1 to 20 of 11857 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Customs valuation of imported rechargeable batteries requires stated grounds creating reasonable doubt before the declared transaction value can be rejected. Valuation must then proceed sequentially under the prescribed methods, supported by contemporaneous import data or valid comparison with identical or similar goods; retail market-inquiry prices alone do not justify enhancement. Payment of differential duty for provisional release does not constitute acceptance of the enhanced value or bar challenge. Where the declared invoice amount was remitted and no evidence showed additional payment, quantity or description discrepancies, misdeclaration, fraud, suppression or wilful misstatement, confiscation, redemption fine and penalty lack foundation. The valuation enhancement and consequential duty demand were unsustainable.
Customs valuation of imported rechargeable batteries requires stated grounds creating reasonable doubt before the declared transaction value can be rejected. Valuation must then proceed sequentially under the prescribed methods, supported by contemporaneous import data or valid comparison with identical or similar goods; retail market-inquiry prices alone do not justify enhancement. Payment of differential duty for provisional release does not constitute acceptance of the enhanced value or bar challenge. Where the declared invoice amount was remitted and no evidence showed additional payment, quantity or description discrepancies, misdeclaration, fraud, suppression or wilful misstatement, confiscation, redemption fine and penalty lack foundation. The valuation enhancement and consequential duty demand were unsustainable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI