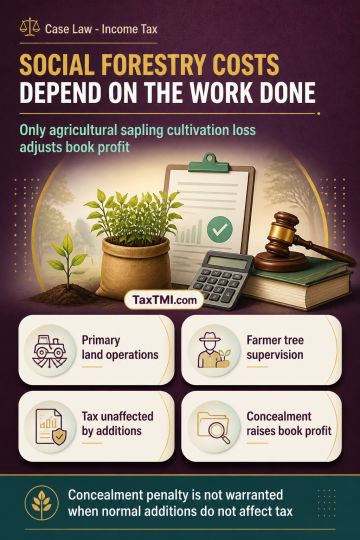
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Customs valuation of imported rechargeable batteries requires stated grounds creating reasonable doubt before the declared transaction value can be rejected. Valuation must then proceed sequentially under the prescribed methods, supported by contemporaneous import data or valid comparison with identical or similar goods; retail market-inquiry prices alone do not justify enhancement. Payment of differential duty for provisional release does not constitute acceptance of the enhanced value or bar challenge. Where the declared invoice amount was remitted and no evidence showed additional payment, quantity or description discrepancies, misdeclaration, fraud, suppression or wilful misstatement, confiscation, redemption fine and penalty lack foundation. The valuation enhancement and consequential duty demand were unsustainable.
Customs valuation of imported rechargeable batteries requires stated grounds creating reasonable doubt before the declared transaction value can be rejected. Valuation must then proceed sequentially under the prescribed methods, supported by contemporaneous import data or valid comparison with identical or similar goods; retail market-inquiry prices alone do not justify enhancement. Payment of differential duty for provisional release does not constitute acceptance of the enhanced value or bar challenge. Where the declared invoice amount was remitted and no evidence showed additional payment, quantity or description discrepancies, misdeclaration, fraud, suppression or wilful misstatement, confiscation, redemption fine and penalty lack foundation. The valuation enhancement and consequential duty demand were unsustainable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI