Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Assignment of contractual property rights attracts capital gains, while penny-stock sale proceeds may be taxed as unexplained cash credits
    Approved valuation reports support improvement-cost claims, while unsupported interior spending cannot qualify for residential reinvestment relief.
    Stock exchange compliance charges qualify as deductible business expenditure; bona fide cess claims cannot trigger under-reporting penalties.
    Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
    Form No. 9A timing remains prospective, while charitable trusts retain independent statutory accumulation within the permissible limit.
    Revised tax audit reports filed before processing require consideration, preventing duplicate tax-withholding disallowances after payer compliance ver...
    Section 12AB registration scope protects charitable hospitals despite overseas training, fee-based care, surplus, and disputed regulatory compliance.
    Intra-group service benefit evidence prevents nil pricing, while associated-enterprise receivables require LIBOR-based interest benchmarking after the...
    Entity-level transfer pricing benchmarking required where interlinked trading and manufacturing transactions cannot be reliably segmented.
    Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
    Secured creditor priority does not release benami property from attachment, while notice challenge fails without proven prejudice.
    Voluntary Customs Duty Deposits May Be Appropriated in Settlement Despite Limitation on Fresh Demand Proceedings
    Writ jurisdiction cannot ordinarily bypass customs appellate remedies, including mandatory pre-deposit, where factual and merits disputes require stat...
    Natural justice requires determination of a non-party's intervention application before final adjudication of an insolvency petition.
    Evidentiary safeguards for statements and electronic records defeated a clandestine-clearance demand lacking independent corroboration entirely.
    Anti-dumping duty on wind turbine gear boxes is limited to embedded castings, not the gear boxes as whole.
    Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
    Customs transaction value requires stated doubt and sequential valuation before market inquiry can support enhancement.
    E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
    Provident-fund dues outside insolvency waterfall require payment with interest, while damages discretion awaits larger-Bench review.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Assignment or transfer of leasehold rights in a GIDC industrial...

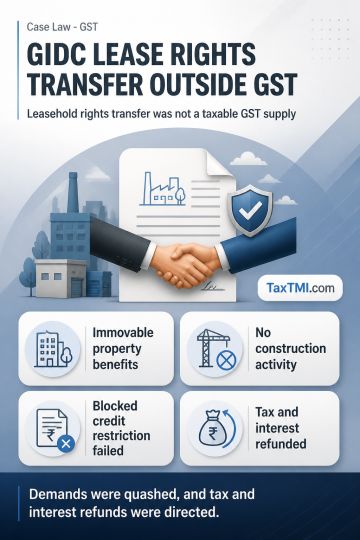
Assignment of GIDC leasehold rights falls outside GST supply, defeating blocked credit demands and fraud-based proceedings.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

GST September 16, 2026 Case Laws HC
Assignment or transfer of leasehold rights in a GIDC industrial plot is characterised as a transfer of benefits arising from immovable property, not a taxable GST supply. GST charged on that transfer therefore lacks legal basis, and input tax credit reversal and interest premised on the assumed levy cannot stand. The blocked-credit restriction for goods or services used in construction of immovable property does not apply where no construction activity occurred. As the underlying transaction is not taxable and the blocked-credit premise fails, allegations of wrongful credit, fraud, wilful misstatement or suppression for section 74 proceedings, including consequential penalty, cannot be sustained. The adjudication and appellate demands were quashed, with refund of tax and interest directed.

Topics

Acts Income Tax