Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
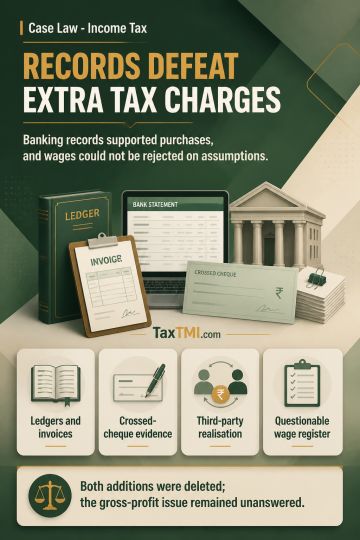
Purchase additions could not be sustained where the taxpayer produced ledgers, invoices, supplier details, registration particulars, bank statements and cheque counterfoils, while undisputed crossed-cheque payments were later realised by third parties. No legal bar then restricted crossed cheques, and the taxpayer could not control their endorsement; absent further inquiry, the High Court restored the first appellate authority's deletion. Wage disallowance based solely on presumed inflation and a doubtful wage register lacked evidentiary support. The High Court set aside the Tribunal's reduced disallowance and restored deletion of both additions; the gross-profit issue remained unanswered.
Purchase additions could not be sustained where the taxpayer produced ledgers, invoices, supplier details, registration particulars, bank statements and cheque counterfoils, while undisputed crossed-cheque payments were later realised by third parties. No legal bar then restricted crossed cheques, and the taxpayer could not control their endorsement; absent further inquiry, the High Court restored the first appellate authority's deletion. Wage disallowance based solely on presumed inflation and a doubtful wage register lacked evidentiary support. The High Court set aside the Tribunal's reduced disallowance and restored deletion of both additions; the gross-profit issue remained unanswered.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881