Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
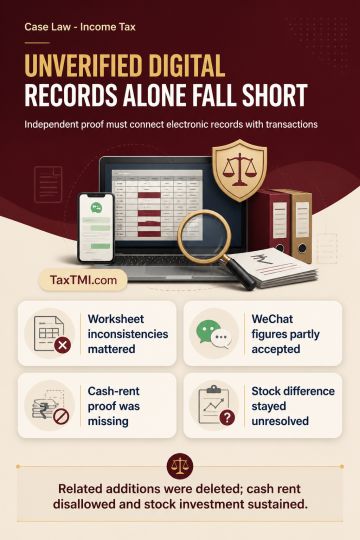
Uncorroborated electronic records cannot alone support additions for unexplained investments, expenditure, interest, sales or debtor balances unless independent evidence establishes their nexus with the assessee and the recorded transactions. Excel worksheets, payment sheets and electronic debtor data containing inconsistencies, without supplier or debtor verification, books, invoices, banking records or other supporting material, failed this standard; the related additions were deleted. WeChat diary figures were accepted only to the extent actually recorded, with gross profit estimated thereon, because no evidence justified applying a multiplier. Cash-rent expenditure was disallowed for want of receipts, ledger entries, landlord confirmation or payment proof, and unexplained stock investment was sustained because the stock difference remained unreconciled.
Uncorroborated electronic records cannot alone support additions for unexplained investments, expenditure, interest, sales or debtor balances unless independent evidence establishes their nexus with the assessee and the recorded transactions. Excel worksheets, payment sheets and electronic debtor data containing inconsistencies, without supplier or debtor verification, books, invoices, banking records or other supporting material, failed this standard; the related additions were deleted. WeChat diary figures were accepted only to the extent actually recorded, with gross profit estimated thereon, because no evidence justified applying a multiplier. Cash-rent expenditure was disallowed for want of receipts, ledger entries, landlord confirmation or payment proof, and unexplained stock investment was sustained because the stock difference remained unreconciled.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881