Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
Concurrent anticipatory-bail jurisdiction permits applications before either forum, while secured evidence may negate custodial interrogation in GST e...
Page of 4881
Press 'Enter' after typing page number.
621 to 640 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
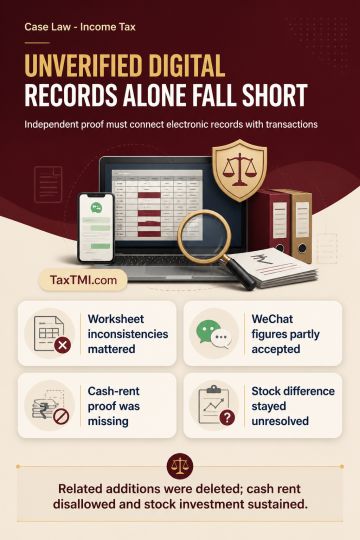
Uncorroborated electronic records cannot alone support additions for unexplained investments, expenditure, interest, sales or debtor balances unless independent evidence establishes their nexus with the assessee and the recorded transactions. Excel worksheets, payment sheets and electronic debtor data containing inconsistencies, without supplier or debtor verification, books, invoices, banking records or other supporting material, failed this standard; the related additions were deleted. WeChat diary figures were accepted only to the extent actually recorded, with gross profit estimated thereon, because no evidence justified applying a multiplier. Cash-rent expenditure was disallowed for want of receipts, ledger entries, landlord confirmation or payment proof, and unexplained stock investment was sustained because the stock difference remained unreconciled.
Uncorroborated electronic records cannot alone support additions for unexplained investments, expenditure, interest, sales or debtor balances unless independent evidence establishes their nexus with the assessee and the recorded transactions. Excel worksheets, payment sheets and electronic debtor data containing inconsistencies, without supplier or debtor verification, books, invoices, banking records or other supporting material, failed this standard; the related additions were deleted. WeChat diary figures were accepted only to the extent actually recorded, with gross profit estimated thereon, because no evidence justified applying a multiplier. Cash-rent expenditure was disallowed for want of receipts, ledger entries, landlord confirmation or payment proof, and unexplained stock investment was sustained because the stock difference remained unreconciled.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881