Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
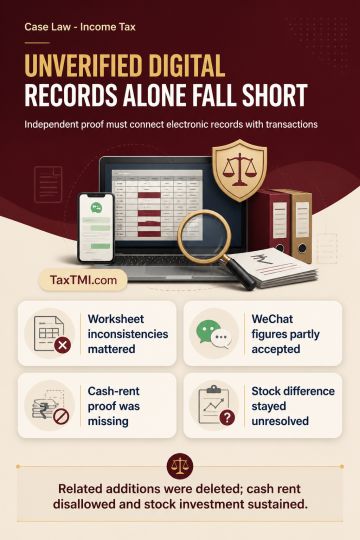
Uncorroborated electronic records cannot alone support additions for unexplained investments, expenditure, interest, sales or debtor balances unless independent evidence establishes their nexus with the assessee and the recorded transactions. Excel worksheets, payment sheets and electronic debtor data containing inconsistencies, without supplier or debtor verification, books, invoices, banking records or other supporting material, failed this standard; the related additions were deleted. WeChat diary figures were accepted only to the extent actually recorded, with gross profit estimated thereon, because no evidence justified applying a multiplier. Cash-rent expenditure was disallowed for want of receipts, ledger entries, landlord confirmation or payment proof, and unexplained stock investment was sustained because the stock difference remained unreconciled.
Uncorroborated electronic records cannot alone support additions for unexplained investments, expenditure, interest, sales or debtor balances unless independent evidence establishes their nexus with the assessee and the recorded transactions. Excel worksheets, payment sheets and electronic debtor data containing inconsistencies, without supplier or debtor verification, books, invoices, banking records or other supporting material, failed this standard; the related additions were deleted. WeChat diary figures were accepted only to the extent actually recorded, with gross profit estimated thereon, because no evidence justified applying a multiplier. Cash-rent expenditure was disallowed for want of receipts, ledger entries, landlord confirmation or payment proof, and unexplained stock investment was sustained because the stock difference remained unreconciled.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881