Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
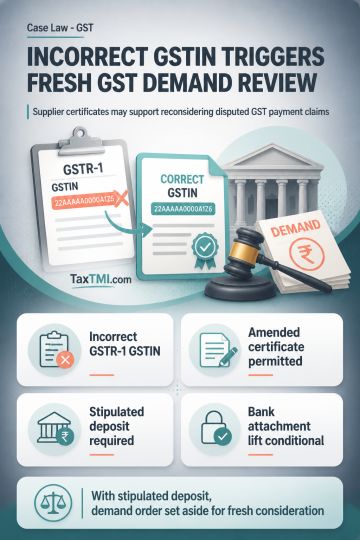
Supplier certification prima facie evidencing receipt of supplies and payment of GST may support reconsideration of a disputed GST demand despite an incorrect GSTIN being reported in GSTR-1. Where the certificate omitted the GSTIN of the person inadvertently recorded in GSTR-1, the taxpayer was permitted to submit an amended certificate identifying those particulars. Subject to the stipulated deposit, the demand order was set aside for fresh consideration after submission of the amended certificate, and the bank attachment was to be lifted upon compliance with that condition.
Supplier certification prima facie evidencing receipt of supplies and payment of GST may support reconsideration of a disputed GST demand despite an incorrect GSTIN being reported in GSTR-1. Where the certificate omitted the GSTIN of the person inadvertently recorded in GSTR-1, the taxpayer was permitted to submit an amended certificate identifying those particulars. Subject to the stipulated deposit, the demand order was set aside for fresh consideration after submission of the amended certificate, and the bank attachment was to be lifted upon compliance with that condition.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891