Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Non-participating bidders cannot disturb concluded liquidation sales on speculative prejudice, while costs for such challenges must remain proportiona...
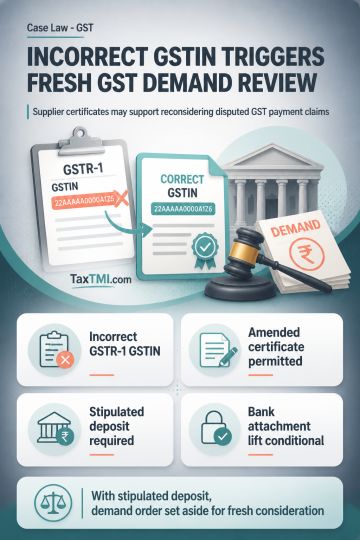
Supplier certification prima facie evidencing receipt of supplies and payment of GST may support reconsideration of a disputed GST demand despite an incorrect GSTIN being reported in GSTR-1. Where the certificate omitted the GSTIN of the person inadvertently recorded in GSTR-1, the taxpayer was permitted to submit an amended certificate identifying those particulars. Subject to the stipulated deposit, the demand order was set aside for fresh consideration after submission of the amended certificate, and the bank attachment was to be lifted upon compliance with that condition.
Supplier certification prima facie evidencing receipt of supplies and payment of GST may support reconsideration of a disputed GST demand despite an incorrect GSTIN being reported in GSTR-1. Where the certificate omitted the GSTIN of the person inadvertently recorded in GSTR-1, the taxpayer was permitted to submit an amended certificate identifying those particulars. Subject to the stipulated deposit, the demand order was set aside for fresh consideration after submission of the amended certificate, and the bank attachment was to be lifted upon compliance with that condition.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888