Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
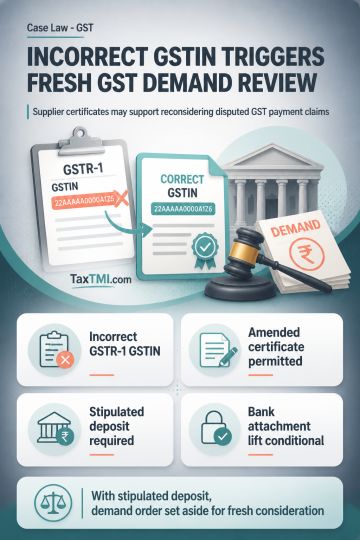
Supplier certification prima facie evidencing receipt of supplies and payment of GST may support reconsideration of a disputed GST demand despite an incorrect GSTIN being reported in GSTR-1. Where the certificate omitted the GSTIN of the person inadvertently recorded in GSTR-1, the taxpayer was permitted to submit an amended certificate identifying those particulars. Subject to the stipulated deposit, the demand order was set aside for fresh consideration after submission of the amended certificate, and the bank attachment was to be lifted upon compliance with that condition.
Supplier certification prima facie evidencing receipt of supplies and payment of GST may support reconsideration of a disputed GST demand despite an incorrect GSTIN being reported in GSTR-1. Where the certificate omitted the GSTIN of the person inadvertently recorded in GSTR-1, the taxpayer was permitted to submit an amended certificate identifying those particulars. Subject to the stipulated deposit, the demand order was set aside for fresh consideration after submission of the amended certificate, and the bank attachment was to be lifted upon compliance with that condition.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4893