Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
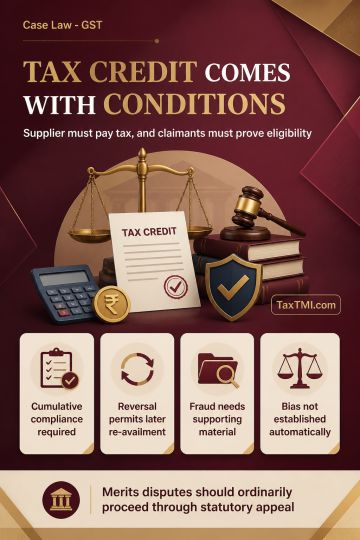
Input tax credit is a conditional statutory entitlement requiring cumulative compliance, including actual tax payment by the supplier. Recipient exposure to supplier default is addressed through reversal and subsequent re-availment of credit, with the claimant bearing the burden of proving eligibility. Fraud-based proceedings require prima facie material supporting allegations of fraud, wilful misstatement or suppression; detailed allegations of fake invoices, bogus supplies and no movement of goods require merits examination. Pre-notice intimation is enabling rather than mandatory, and investigation and adjudication by the proper officer do not alone establish bias. Merits disputes should ordinarily proceed through the statutory appellate remedy.
Input tax credit is a conditional statutory entitlement requiring cumulative compliance, including actual tax payment by the supplier. Recipient exposure to supplier default is addressed through reversal and subsequent re-availment of credit, with the claimant bearing the burden of proving eligibility. Fraud-based proceedings require prima facie material supporting allegations of fraud, wilful misstatement or suppression; detailed allegations of fake invoices, bogus supplies and no movement of goods require merits examination. Pre-notice intimation is enabling rather than mandatory, and investigation and adjudication by the proper officer do not alone establish bias. Merits disputes should ordinarily proceed through the statutory appellate remedy.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888