Self-assessed import entries remain appealable, while bona fide classification disputes without misdeclaration cannot justify confiscation or penaltie...
Actual-user customs exemption conditions permit turnkey project transfers when imported windmill components are exclusively used for installation and ...
Customs offence disqualification excludes civil contraventions, preventing refusal of a private bonded warehouse licence based solely on monetary pena...
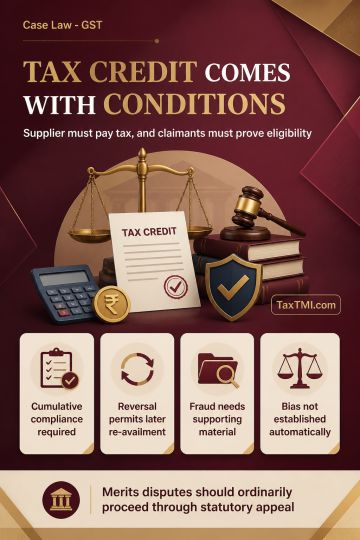
Input tax credit is a conditional statutory entitlement requiring cumulative compliance, including actual tax payment by the supplier. Recipient exposure to supplier default is addressed through reversal and subsequent re-availment of credit, with the claimant bearing the burden of proving eligibility. Fraud-based proceedings require prima facie material supporting allegations of fraud, wilful misstatement or suppression; detailed allegations of fake invoices, bogus supplies and no movement of goods require merits examination. Pre-notice intimation is enabling rather than mandatory, and investigation and adjudication by the proper officer do not alone establish bias. Merits disputes should ordinarily proceed through the statutory appellate remedy.
Input tax credit is a conditional statutory entitlement requiring cumulative compliance, including actual tax payment by the supplier. Recipient exposure to supplier default is addressed through reversal and subsequent re-availment of credit, with the claimant bearing the burden of proving eligibility. Fraud-based proceedings require prima facie material supporting allegations of fraud, wilful misstatement or suppression; detailed allegations of fake invoices, bogus supplies and no movement of goods require merits examination. Pre-notice intimation is enabling rather than mandatory, and investigation and adjudication by the proper officer do not alone establish bias. Merits disputes should ordinarily proceed through the statutory appellate remedy.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888