Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
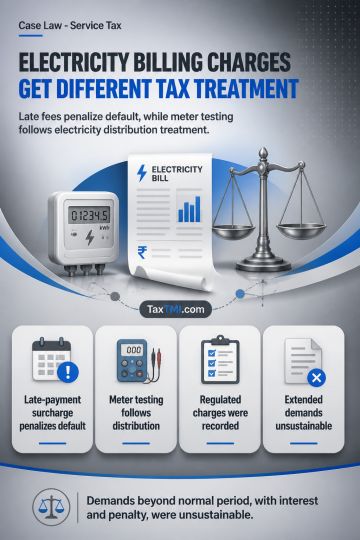
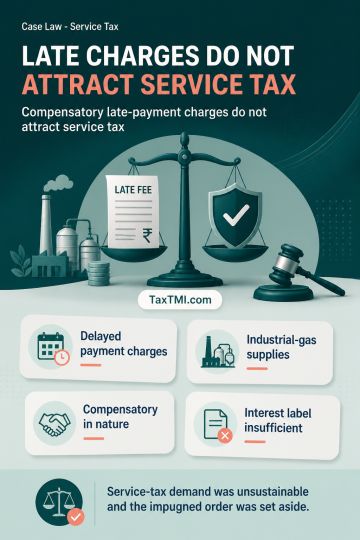
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
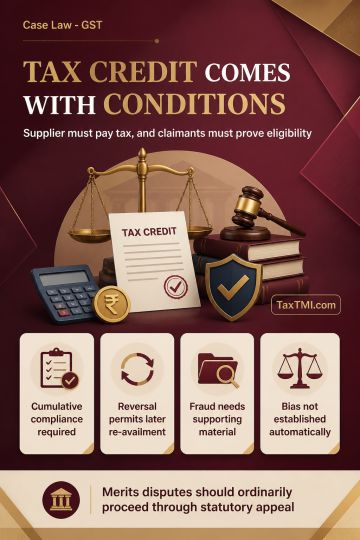
Input tax credit is a conditional statutory entitlement requiring cumulative compliance, including actual tax payment by the supplier. Recipient exposure to supplier default is addressed through reversal and subsequent re-availment of credit, with the claimant bearing the burden of proving eligibility. Fraud-based proceedings require prima facie material supporting allegations of fraud, wilful misstatement or suppression; detailed allegations of fake invoices, bogus supplies and no movement of goods require merits examination. Pre-notice intimation is enabling rather than mandatory, and investigation and adjudication by the proper officer do not alone establish bias. Merits disputes should ordinarily proceed through the statutory appellate remedy.
Input tax credit is a conditional statutory entitlement requiring cumulative compliance, including actual tax payment by the supplier. Recipient exposure to supplier default is addressed through reversal and subsequent re-availment of credit, with the claimant bearing the burden of proving eligibility. Fraud-based proceedings require prima facie material supporting allegations of fraud, wilful misstatement or suppression; detailed allegations of fake invoices, bogus supplies and no movement of goods require merits examination. Pre-notice intimation is enabling rather than mandatory, and investigation and adjudication by the proper officer do not alone establish bias. Merits disputes should ordinarily proceed through the statutory appellate remedy.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4843