Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
Concurrent anticipatory-bail jurisdiction permits applications before either forum, while secured evidence may negate custodial interrogation in GST e...
Page of 4881
Press 'Enter' after typing page number.
621 to 640 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
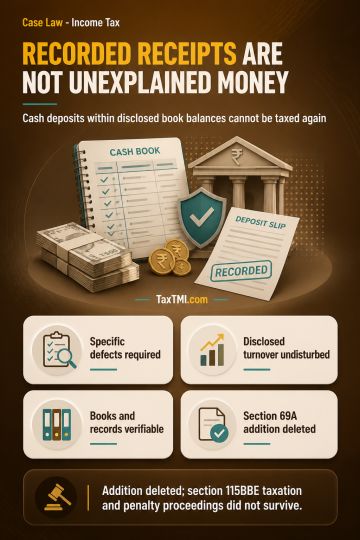
Rejection of books of account under section 145(3) requires specific defects that prevent correct determination of business income; suspicion about cash receipts is insufficient where disclosed turnover and trading results remain undisturbed and computerised books and supporting records are offered for verification. Section 69A does not apply to money recorded in the books merely because the books are formally rejected. Cash deposits within recorded cash balances, arising from disclosed sales and trade-debtor realisations, cannot be assessed again as unexplained income unless their nexus with the recorded business is disproved. The section 69A addition was deleted, with consequential taxation under section 115BBE and penalty proceedings not surviving.
Rejection of books of account under section 145(3) requires specific defects that prevent correct determination of business income; suspicion about cash receipts is insufficient where disclosed turnover and trading results remain undisturbed and computerised books and supporting records are offered for verification. Section 69A does not apply to money recorded in the books merely because the books are formally rejected. Cash deposits within recorded cash balances, arising from disclosed sales and trade-debtor realisations, cannot be assessed again as unexplained income unless their nexus with the recorded business is disproved. The section 69A addition was deleted, with consequential taxation under section 115BBE and penalty proceedings not surviving.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881