Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
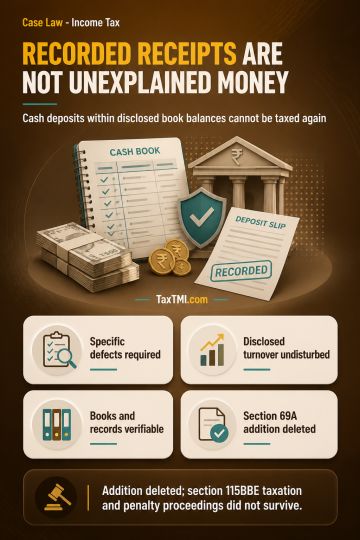
Rejection of books of account under section 145(3) requires specific defects that prevent correct determination of business income; suspicion about cash receipts is insufficient where disclosed turnover and trading results remain undisturbed and computerised books and supporting records are offered for verification. Section 69A does not apply to money recorded in the books merely because the books are formally rejected. Cash deposits within recorded cash balances, arising from disclosed sales and trade-debtor realisations, cannot be assessed again as unexplained income unless their nexus with the recorded business is disproved. The section 69A addition was deleted, with consequential taxation under section 115BBE and penalty proceedings not surviving.
Rejection of books of account under section 145(3) requires specific defects that prevent correct determination of business income; suspicion about cash receipts is insufficient where disclosed turnover and trading results remain undisturbed and computerised books and supporting records are offered for verification. Section 69A does not apply to money recorded in the books merely because the books are formally rejected. Cash deposits within recorded cash balances, arising from disclosed sales and trade-debtor realisations, cannot be assessed again as unexplained income unless their nexus with the recorded business is disproved. The section 69A addition was deleted, with consequential taxation under section 115BBE and penalty proceedings not surviving.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881