Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
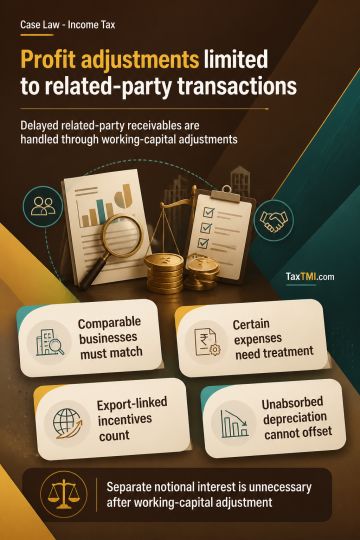
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
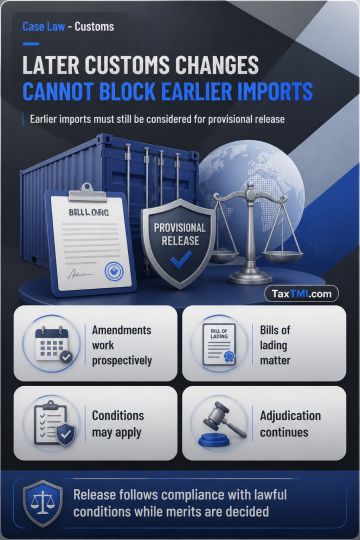
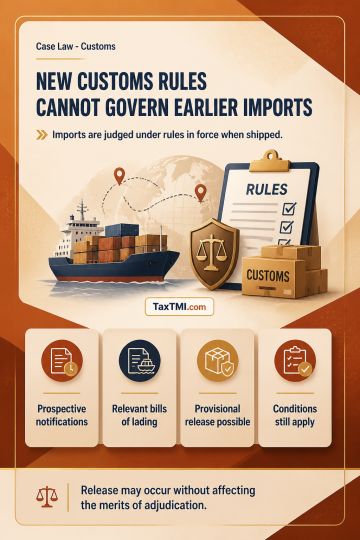
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Assessment-order limitation depends on when the order is made or passed within the statutory period, not on later dispatch, communication or receipt; a dated order remains timely absent material showing it was actually made later. Rental income reflected in Form 26AS cannot be added without verifying whether timing differences from straight-line lease-rental recognition have already been taxed in another year. Interest on refinancing may qualify for deduction under section 24(b) only where a direct nexus connects the original borrowing, property acquisition or construction, and subsequent loan. Tenant-wise reconciliation and refinancing fund-flow evidence require fresh verification; the limitation challenge was rejected, while the rental and interest issues were remanded.
Assessment-order limitation depends on when the order is made or passed within the statutory period, not on later dispatch, communication or receipt; a dated order remains timely absent material showing it was actually made later. Rental income reflected in Form 26AS cannot be added without verifying whether timing differences from straight-line lease-rental recognition have already been taxed in another year. Interest on refinancing may qualify for deduction under section 24(b) only where a direct nexus connects the original borrowing, property acquisition or construction, and subsequent loan. Tenant-wise reconciliation and refinancing fund-flow evidence require fresh verification; the limitation challenge was rejected, while the rental and interest issues were remanded.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881